The Hidden Impact of CityFibre’s UK Project Gigabit Broadband Contracts Retreat | ISPreview UK

Original article ISPreview UK:Read More

At the end of last month CityFibre announced that they’d reached an agreement with the Government to significantly cut the roll-out scope of their Project Gigabit broadband contracts. At the time this was expressed as being because commercial builds by rivals would reach further than originally expected. But this overlooked the hidden gap of premises that have been left with no alternative plans.

Just to recap. CityFibre previously held ten Project Gigabit contracts – originally representing over £920m of government funding for a subsidised build to 557,000 premises in “hard-to-reach” rural areas (1.36 million if we included their supporting commercial build). But in May 2026 these were “re-scoped in response to the accelerated rollout of commercially funded full fibre” (here).

NOTE: The £5bn Project Gigabit scheme aims to help extend gigabit broadband (1Gbps+) networks to “nationwide” coverage (c.99% of UK premises) by 2032, focusing mostly on the final 10-20% in hard-to-reach areas. Some 90% of premises can already access such a network (here) and Ofcom are forecasting this could reach up to 95% by January 2029 (here).

In practice, the agreement saw the operator abandon their £58.6m Project Gigabit contract for Nottinghamshire and West Lincolnshire (Lot 10) and significantly reduce the roll-out for most of the nine other contracts that remained. CityFibre now expects to connect a total of 450,000 rural and harder-to-reach premises by 2030, including 226,000 subsidised through Project Gigabit (c.70k of that 226k has already been completed).

On the surface this sounded like gigabit broadband coverage would not be negatively impacted because those areas descoped by CityFibre would still be reached commercially, except we soon learnt that wasn’t the case.

Explaining the real change

The first thing to understand here is that Project Gigabit contracts do change a bit over time due to various different reasons – informed by regular ‘Open Market Reviews’ of existing UK deployment plans. For example, commercial operators may expand or reduce their roll-out plans in the same region, which can reduce or grow the scope for public investment within those same contracted areas.

The contracted operator could also find the deployment to be more expensive, or possibly even cheaper, than previously envisaged. Such adjustments may occur due to changes in build costs and interest rates / inflation, as well as any unexpected obstacles to street works or greater efficiencies of build than planned or expected.

Suffice to say, there’s often a bit of a yo-yo movement as contracts progress (they may expand or even shrink over time), although in this case CityFibre has significantly reduced their plans. The catch is that commercial builds usually have a much more modest impact upon Project Gigabit contracts, which tend to be focused on rural areas where rivals often struggle to build FTTP at pace or scale.

On top of that, ISPreview soon began receiving quite a bit of feedback from those impacted by the change, which strongly indicated that some communities previously covered by these contracts were being left with no future plans for gigabit broadband coverage – either commercially or via subsidised builds. When challenged on this, CityFibre informed us that the “majority” of impacted premises originally due to be upgraded by CityFibre through Project Gigabit will now be connected commercially.

A spokesperson for CityFibre told ISPreview:

“The majority of premises due to be upgraded by CityFibre through Project Gigabit will now be connected commercially, meaning no public funding is required. Given the extent of commercial build in these areas, and the options for alternative delivery to the remaining premises, these changes will not affect BDUK’s ability to achieve the UK government’s target of 99% UK gigabit coverage by 2032. The plan for the premises that CityFibre are no longer building on is a question for BDUK.”

The question that’s harder to answer here is how do they define “majority“, since 51% can be just as much a “majority” as 99% – the gap left with no build by either Project Gigabit or commercial coverage could thus either be a few tens, hundreds or thousands of premises. We simply don’t know, so we asked the Government’s Building Digital UK (BDUK) agency, and they couldn’t give us a completely clear answer either (we assume the final third of premises being referenced below includes those still under contract and those being left in limbo).

A Government (BDUK/DSIT) spokesperson said:

“As commercial gigabit broadband rollout has accelerated across the UK, we’ve agreed changes to CityFibre’s Project Gigabit contracts to ensure we are getting the best deal for taxpayers.

Two thirds of premises that were due to be upgraded by CityFibre through Project Gigabit either already have access to a gigabit capable connection, or will now be connected commercially – meaning public funding is no longer required.

We are already engaging with other suppliers so that the remaining premises are upgraded at pace and communities get the connectivity they deserve. These changes will not affect our ability to hit our target of 99% UK gigabit coverage by 2032.”

In fairness, BDUK do regularly publish detailed datasets setting out which premises are in commercial rollout plans, and which are in Project Gigabit contracts. But we don’t have the resources to be able to process such complex data in order to accurately identify the gap left in limbo by CityFibre for each contract, which in any case is an answer that BDUK should already have and yet the government chose not to share it when asked.

However, the Arundel and South Downs MP, Andrew Griffith, recently asked a similar question about the specific situation in West Sussex. As we noted in our original article, CityFibre’s £100m Project Gigabit contract for East and West Sussex had originally aimed to reach c.52,000 hard-to-reach premises, but after the change they would now only tackle around 13,000 premises for £25.2m.

According to the government’s response to Mr Griffith, of the 6,490 premises in Arundel and South Downs that were included in the original scope of Project Gigabit to be delivered by CityFibre, some 5,890 have now been “de-scoped” from the contract. Out of those, 850 now have access to gigabit broadband, while just 890 are included in future commercial delivery plans, which is said to leave 4,150 premises without either a commercial or subsided build plan.

The above reflects just one area inside one of the contracts, but it’s not unreasonable to expect that the gap now likely to be left in limbo by CityFibre’s change across all contracts may be bigger than they’d like to admit. The good news, if you can call it that, is we have seen similar situations before where contracts have been abandoned or scaled-back, but where alternative solutions were later found.

The most common fix is for such premises to be swapped into one of Openreach’s larger Type C (Cross-Regional) contracts under Project Gigabit (no other suppliers tackle Type C), which is precisely what that framework exists to help tackle (examples here, here, here and here).

According to our sources, a good portion of the premises that have been left in gigabit broadband limbo by CityFibre’s retreat should hopefully soon end up being moved into a Type C contract, assuming there’s no significant interest from other suppliers.

However, the situation will inevitably cause additional delays to delivery, since any new supplier will naturally need to conduct its own work to figure out which premises they can and cannot tackle, as well to plan the necessary resources and to conduct engineering surveys. History suggests that this can add an extra year or so to the roll-out plan for an area vs the original plan.

Streetwave UK Reveals Quality of Mobile Network Coverage in Neath Port Talbot | ISPreview UK

Original article ISPreview UK:Read More

Network analyst firm Streetwave has published the partial results from a new study, which compared real-world mobile network (4G, 5G) coverage and mobile broadband performance across the Neath Port Talbot Council (NPTC) area in Wales, which sits just next to Swansea and is home to around 145,000 people.

Just to recap. Streetwave works by harnessing waste bin (refuse) collection lorries to map mobile network coverage and data speeds across various parts of the UK (e.g. here, here, here, here and here). In this setup, refuse trucks are installed with several off-the-shelf Smartphones using special software, which run continuous network tests (once every 20 metres in rural areas and 5m in urban areas) as the vehicles go around their routes.

NOTE: Throughput speed (consumer experience), signal strength, network generation and frequency band information are collected across all the main UK mobile operators.

The data they collect is often then used by local authorities to help identify areas that may require additional intervention in order to improve local mobile coverage and or network capacity, while also giving locals access to some of this data via address-based coverage checkers and interactive maps (https://app.streetwave.co/coverage-checker/) – this now includes the new data for Neath Port Talbot.

The survey of the Neath Port Talbot area collected data from all four of the primary mobile networks (EE, Vodafone, O2 and Three UK) and across over 800km of roads in the council between 5th to 26th March 2026. Overall Streetwave found that the average Basic Coverage scores for the operators across the council were 71.5%, which fell away to 54.5% for Good Coverage. “In some wards and parishes, the average ‘Good Coverage’ falls below 35%, highlighting the ongoing digital divide many rural communities in the council face,” said the brief update.

Sadly they haven’t included any operator specific results this time or data for download/upload speeds, but you can find location specific figures on the aforementioned map. Streetwave defines Basic Coverage as reflecting locations where the mobile network provides users with data speeds of above 1Mbps download, 0.5Mbps upload, and below 100ms (milliseconds) of latency (i.e. supporting only the most basic of use cases or needs).

The company defines Good Coverage as being locations where the mobile networks provide at least 5Mbps download, 1.5Mbps upload, and less than 50ms latency – supporting a wider range of everyday tasks including video calls, remote working, and higher quality streaming. The results were as follows.

Reliance Jio lining up India’s largest IPO | Total Telecom

Original article Total Telecom:Read More

News

India’s largest mobile operator is targeting a landmark public listing as it ramps up investments in AI, cloud and next-generation digital infrastructure.

Reliance Jio’s MD and Chairman Mukesh Ambani has announced that the company will file the initial public offering (IPO) papers with the Securities and Exchange Board of India (SEBI) later today.

The IPO could raise around $3.8 billion, according to analyst estimates, making it India’s largest IPO to date.

“The proposed listing of Jio will demonstrate to the world that India can build technology companies of global scale, global capability, and global value,” said Ambani at the company’s Annual General Meeting.

Backed by the billionaire Ambani, Reliance Jio Infocomm burst onto India’s mobile scene in 2016, with its discount prices triggering a major price war. Since then, the company has soared to become the country’s largest mobile operator with over 500 million customers.

The listing is expected to be closely watched by investors seeking exposure to India’s fast-growing digital economy. Jio has expanded well beyond mobile connectivity in recent years, building out a portfolio that includes fibre broadband, enterprise services, cloud offerings, digital payments and connected devices.

AI was also a significant focus of the meeting, with Ambani calling for India to continue its efforts to embrace AI and develop its own platforms, saying that the country should be a creator of AI as well as a consumer.

Jio is investing heavily in AI, with Ambani saying earlier this year that the company would invest around $110 billion over seven years to build India’s AI backbone infrastructure.

The company’s JioBrain platform, which it uses for network planning, predictive maintenance, resource optimisation and customer service automation, notably won the AI Innovation award at the World Communication Awards 2025.

Also in the news
TELUS and L-SPARK give Canadian startups access to AI supercomputer
Belden to acquire RUCKUS Networks for $1.85bn
VMO2 taps Suffolk solar farm for 10 years of clean energy

The post Reliance Jio lining up India’s largest IPO appeared first on Total Telecom.

Broadband ISP Olilo Sign UK Government Charter to Stop Unexpected Bill Hikes | ISPreview UK

Original article ISPreview UK:Read More

The relatively new broadband provider Olilo has today become the latest retail ISP to sign up to the Government’s Telecoms Consumer Charter (TCC), which was first introduced in February 2026 and follows the addition of Hyperoptic at the start of this week.

The Government has so far succeeded, via the TCC, in getting all the major and a few smaller UK broadband and phone providers to make a commitment to “stop unexpected bill increases“, make social tariffs easier to access and provide clear contract / package information etc. – including BT (EE, Plusnet), Virgin Media and O2, VodafoneThree (Vodafone and Three UK), Sky Broadband, TalkTalk, KCOM, CommunityFibre, WightFibre and Hyperoptic.

NOTE: The new charter is also supported by the Internet Service Providers Association (ISPA) and the Independent Networks Cooperative Association (INCA).

The good news is that Olilo has now signed up to the charter too, although we can’t yet see a social tariff on their website. But it should be said that the TCC doesn’t have any real teeth, won’t do anything to stop mid-contract price hikes themselves and nor does it address the unfairness of how such price hikes are currently being applied (e.g. applying the same flat c.£2-£4 monthly increase to those who pay just c.£20 a month and those who pay c.£100 – disproportionately targeting those least able to afford it).

The TCC was instead a late reaction to last year’s controversial decision by mobile operator O2 (here), which suddenly increased the cost of their existing mid-contract price hikes policy and applied that to their existing customers too (i.e. those who had signed-up via the previous policy were forced to accept the new one and its higher prices). Of course, providers that aren’t yet signed up to the TCC could still behave in this way.

New Report Examines the UK’s Public Switched Telephone Network Switch Off | ISPreview UK

Original article ISPreview UK:Read More

A new independent research report has been published by BroadbandSwitch.uk, which provides a fairly detailed and useful overview of Britain’s move to switch-off the old analogue phone network on 31st January 2027, which was previously delayed from the original end of 2025 deadline in order to protect vulnerable consumers.

Just to recap. Openreach are withdrawing their old Wholesale Line Rental (WLR) products as part of this change, while BT are retiring their related Public Switched Telephone Network (PSTN). But at present around 1.9 million UK lines are yet to switch to a digital alternative and the focus of the remaining effort is largely on helping those who use vital home telecare systems (e.g. elderly, disabled – vulnerable users), which aren’t always compatible with newer IP-based phone services (telecare providers were slow to adapt).

The Last Dial Tone paper doesn’t say anything that we haven’t reported on before, but we do think it’s one of the better overarching summaries. The report’s modelling also estimates that a residual tail of between 150,000 and 400,000 lines will not be migrated in time, although Openreach are expecting something more in the high tens of thousands.

The good news, as recently reported (here), is that consumer lines won’t face a hard disconnection on the deadline and there will be an emergency solution for those who fail to migrate. Business lines, however, won’t benefit from the same protections and will need to get a move on.

Dr Alex J. Martin-Smith, Report Author, said:

My hypothesis, stated plainly so it can be marked against events: the headline date will hold, but completion will be achieved partly on paper. A residual tail of lines, our modelling suggests somewhere between 150,000 and 450,000, will not be migrated in time. Instead they will be caught by transitional products that BT and Openreach have quietly pre-built for exactly this purpose: an emergency-calls-only line called EVAc, and analogue-style stopgaps known as PDPL and SOTAP that run to around 2030. The platform retires on schedule. A minority keeps a dial tone through the side door. That is a soft landing, not a clean finish, and not a delay.

Why lean this way? Three reasons run through this report. First, the network is failing in plain sight: it consumes around 1% of British energy usage, suffered more than 2,600 major incidents in a single year, and runs on parts nobody manufactures any more. Second, the date is a commercial decision, not a law, and the government has said it will not legislate a pause. Third, and decisively, the escape hatch already exists. The argument that forced the 2023 pause, that vulnerable people would be cut off, has been structurally defused by products designed to make sure nobody is.

We put the probability of this soft landing at 72%, a formal further delay at 23%, and a genuinely clean completion at just 5%. Part Three shows the working, and page 26 publishes the exact criteria by which we will score ourselves after the event. Authority is cheap to claim and expensive to demonstrate. We have chosen the expensive route.

June 2026 UK Contract Progress of the Project Gigabit Broadband Rollout | ISPreview UK

Original article ISPreview UK:Read More

The Government’s Building Digital UK (BDUK) agency has today released their June 2026 update on the delivery progress of contracts awarded under the £5bn Project Gigabit broadband rollout scheme. The update reveals that some 271,460 contracted premises (up from 256,680 in May 2026) have so far been covered out of a planned total of 839,340 (32% complete).

Just to remind. The figures in this update are not directly comparable to the figures published in BDUK’s annual general statistics releases. This is because today’s report tracks the number of contracted premises to which a supplier has delivered a gigabit-capable connection under the main Gigabit Infrastructure Subsidy (GIS) programme, whereas the general statistics also include gigabit premises delivered via any public / BDUK subsidy (i.e. that includes other schemes too, like gigabit vouchers and contracts that pre-date Project Gigabit).

NOTE: Project Gigabit aims to help extend gigabit broadband (1000Mbps+) ISP networks to “nationwide” coverage (c.99% of UK premises) by 2032, focusing mostly on the final 10-20% in hard-to-reach areas. Some 90% of premises can already access such a network (here) and Ofcom are forecasting this could reach up to 95% by January 2029 (here).

So far, most of the country’s gigabit-capable broadband coverage has been delivered by commercial deployments (predominantly focused on urban and semi-urban areas), while Project Gigabit focuses on the final bits that they fail to reach (usually rural areas). The project has already committed most of its budget up to 2030, but there are still some contracts yet to be awarded and others that have been scaled-back or switched suppliers (e.g. here, here, here, here, here and here).

Otherwise, it’s worth remembering that these contracts were all awarded at different times and are thus at very different stages of development (some started several years apart). A few of the listed contracts have already completed their delivery, such as Wessex Internet’s build for North Dorset and GoFibre’s roll-outs for County Durham and North Northumberland. Meanwhile, others, such as Openreach’s new contract for Cheshire (here), were only added in the April 2026 update.

Suffice to say, it’s important to understand the context behind each contract before judging delivery progress, since a face-value assessment will often overlook key realities. Speaking of which, some of the contracted figures may differ from the original announcements, which reflects the usual modifications (i.e. the scope of delivery can increase or decrease, such as due to commercial builds by rival operators going further than expected or builds costing more than expected etc.).

The progress this time has been steady for many contracts, although BDUK did note that they’d removed 310 premises from Wessex Internet’s contract for North Dorset, which will be re-added at a later date. Take note that the ebb and flow of a build can vary a lot from month to month as different phases starts and finish. We also note that this list still doesn’t seem to include two of GoFibre’s contracts in Scotland, which is despite those now delivering coverage.

Project Gigabit – Contracted Premises and Built Premises by Contract (June 2026)

Contract Supplier Contracted Premises Built Contracted Premises (June 2026) Monthly Change % Complete
Bedfordshire, Northamptonshire and Milton Keynes CityFibre 5,890 4,660 510 79%
Bucks, Herts and East of Berks CityFibre 6,090 3,810 170 63%
CO1 Lancashire, West Berkshire, Staffordshire, Surrey, Hertfordshire, Wiltshire and Gloucestershire Openreach 60,180 17,170 2,710 29%
CO2 Devon, Mid Wales and South East Wales Openreach 41,140 9,810 600 24%
CO3 North Herefordshire, North Wales, Shropshire and South West Wales Openreach 65,120 1,240 0 2%
CO4 South Devon, Mid Devon and North Somerset Openreach 37,110 3,150 0 8%
CO5 Essex and North East England Openreach 35,300 880 0 2%
CO6 Rest of Scotland Openreach 77,640 5,680 2,000 7%
CO7 Worcestershire Openreach 22,600 170 50 1%
CO8 Cheshire Openreach 18,460 0 0 0%
Cambridgeshire CityFibre 18,230 10,840 -10 59%
Central Cornwall Wildanet 6,940 6,940 0 100%
Cornwall and Isle of Scilly Wildanet 14,430 3,660 120 25%
Cumbria Fibrus 53,540 34,830 1,500 65%
Derbyshire Connect Fibre 13,290 1,200 0 9%
Dorset and South Somerset Wessex internet 19,560 4,520 680 23%
Durham GoFibre 4,440 4,440 0 100%
East Gloucestershire Gigaclear 3,550 1,800 0 51%
East and West Sussex CityFibre 12,760 2,970 0 23%
Hampshire CityFibre 29,420 6,970 200 24%
Kent CityFibre 8,750 2,530 210 29%
Leicestershire and Warwickshire CityFibre 22,480 10,310 210 46%
Lincolnshire and East Riding Quickline 47,800 20,610 1,560 43%
New Forest Wessex internet 12,730 10,390 140 82%
Norfolk CityFibre 32,670 12,770 260 39%
North Dorset Wessex internet 6,480 6,170 -310 95%
North East Staffordshire Connect Fibre 5,960 2,410 330 40%
North Oxfordshire Gigaclear 4,180 3,750 60 90%
North Shropshire Freedom Fibre 3,410 1,900 630 56%
Northern North Yorkshire Quickline 34,490 10,980 740 32%
Northumberland GoFibre 3,830 3,830 0 100%
South Oxfordshire Gigaclear 5,120 3,200 60 63%
South West Cornwall Wildanet 6,400 6,400 0 100%
South Wiltshire Wessex internet 18,790 7,230 840 38%
South Yorkshire Quickline 13,290 9,270 190 70%
Suffolk CityFibre 38,350 17,960 600 47%
West and Parts of North Yorkshire Quickline 28,950 17,050 740 59%
TOTAL   839,340 271,460 14,780 32%

For some extra context, you can check out the previous figures for May 2026 (here)

140 Government Funded 4G Mobile Mast Upgrades Now Live Across UK | ISPreview UK

Original article ISPreview UK:Read More

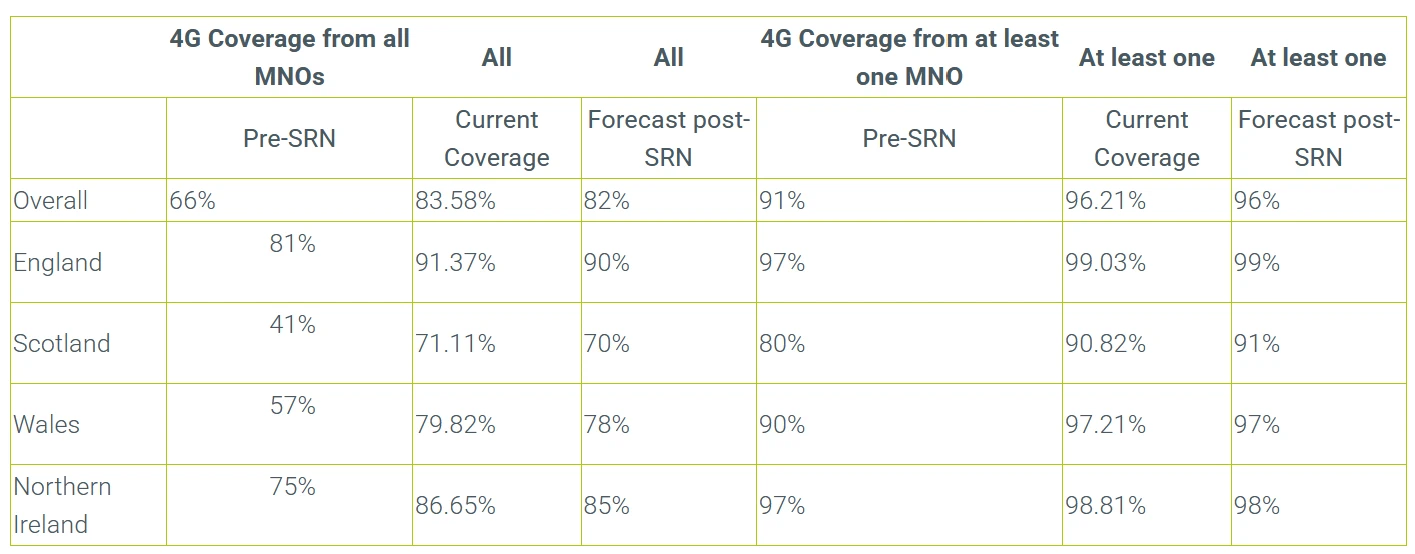
The UK Government has confirmed that a total of 140 publicly-funded rural 4G (mobile broadband) mast upgrades have now gone live across the United Kingdom (up from 100 at the end of 2025), which includes new sites in England, Wales and Scotland as part of the industry-led £1bn Shared Rural Network (SRN) project. But more are set to follow before 2027.

The SRN – originally supported by a commitment of £501m in public funding and £532m of private investment from operators – involves both the reciprocal sharing of existing masts in certain areas and the demand-led building and sharing of new masts in others between the operators.

NOTE: The target varies between regions, thus 4G cover from at least one operator is expected to reach 98% in England, 91% in Scotland, 95% in Wales and 98% in N.Ireland. But this falls to 90% in England, 74% in Scotland, 80% in Wales and 85% in N.Ireland when looking at coverage from all MNOs combined.

The SRN has already achieved its first target a year ahead of schedule by ensuring that 96% of the UK’s landmass can now access a 4G mobile network from at least one operator (here), although the coverage range drops to 89-90% when looking look across all operators (here). The project is now focused on tackling the second target to reduce Total Not-Spot (TNS) areas by January 2027.

Most of the early work on this project has involved private investment from the main mobile network operators – O2 (Virgin Media), Vodafone (VodafoneThree) and EE (BT). But over the past few years we’ve also seen government-funded mast upgrades and new site builds taking place in other parts of the country.

Regional Summary (Mobile UK)

Wales

Wales has seen a significant portion of this year’s rollout, with 11 new masts activated to bring the nation’s total to 55 government-funded SRN sites. The upgrades mean that residents and visitors to historically isolated spots — such as Nant Gwynant in Snowdonia, Capel y Ffin, and Manafon — can now access reliable 4G mobile internet regardless of their network provider.

Scotland

In the Highlands, a new TNS site has gone live at Scardroy, situated roughly 45km west of Inverness. The TNS portion of the programme explicitly targets areas that previously had no coverage from any mobile operator.

England

Across northern England, dozens of mast upgrades are being switched on to address historic blackspots. In Yorkshire, 4 new masts (bringing the regional total to 11) have gone live in locations like Halton Gill, Westerdale, and Arncliffe. Meanwhile, in the North East and Cumbria, a further 2 masts have been activated (bringing their total to 16), providing improved digital infrastructure to communities in Sharperton and Longsleddale.

With further work currently underway across multiple sites, the programme continues its rollout to narrow the digital divide between urban and rural parts of the UK.

We understand that there are around 40 new and upgraded masts that still need to be completed before the final deadline.

Current SRN 4G Geographic Coverage Progress (June 2026)

SRN-Coverage-Progress-June-2026

Tribunal Says BT is a UK Public Authority for Environmental Regs, But Not Openreach | ISPreview UK

Original article ISPreview UK:Read More

A Tribunal has ruled that broadband and phone provider BT’s role, obligations and statutory powers make it sufficiently public in character for environmental-information purposes, but network access provider Openreach’s separate corporate status means it does not cross that same legal threshold.

The case reflected an appeal by BT and Openreach, which had been raised after the Information Commissioner’s Office (ICO) initially determined that both of the operators should fall within Regulation 2(2) of the Environmental Information Regulations 2004 (EIR) – effectively designating them as “public authorities” for the purpose of related information requests by members of the public or others.

The ICO’s view was that both should be subject to such EIR related information requests because they carry out services in the public interest, operate under a statutory framework (e.g. Ofcom’s various rules, BT’s broadband USO etc.), hold special legal powers beyond those available to normal private companies and have a big impact on environmental matters. Not to mention that such networks are now considered essential national infrastructure.

In short, the ICO argued that all of this meant the environmental information held by both companies should be accessible to the public in the same way as information held by many public bodies. But as commercial operators this was naturally something that BT and Openreach opposed.

The Tribunal examined all of this in some detail (see the ruling) and appeared concerned that the ICO’s argument might end up meaning that almost any contractor, employee or agent acting for a public authority could themselves become a public authority. But they also recognised that Openreach’s legal separation from BT was a significant difference, thus what may apply to once doesn’t necessarily apply to the other.

Judge Kiai said:

“The Tribunal concludes that BT is a “public authority” for the purposes of the Environmental Information Regulations 2004 by virtue of regulation 2(2)(c): BT is entrusted under the applicable national law regime with the performance of services of public interest which have the requisite nontrivial nexus with the environment, and for that purpose is vested with special powers going beyond the normal rules applicable between private persons.

By contrast, Openreach is not a “public authority” under regulation 2(2)(c), because it is not itself vested under national law with the relevant special powers, and the operational fact that it acts as BT’s agent does not satisfy the distinct “vesting” requirement.

Nor is Openreach a public authority under regulation 2(2)(d), because the Commissioner has not shown, on the evidence taken as a whole, that BT is in a position to exert decisive influence such that Openreach does not determine in a genuinely autonomous manner the way it performs the relevant functions. It follows that the appeal is allowed only to the extent that the Decision Notice relating to Openreach must be substituted and is otherwise dismissed.”

The split decision is good news for Openreach, as it will not now have to deal with the complex extra admin and costs that would come from needing to respond to environmental information requests (similar to those imposed on some public bodies). But obviously the situation for BT is exactly the opposite.

A BT Group spokesperson told ISPreview:

“We note the Tribunal’s conclusions on BT and are carefully considering the judgment and our options. The issues engaged raise important points of principle about the scope of the Environmental Information Regulations as applied to commercial companies operating in competitive markets. We welcome the Tribunal’s finding that Openreach is not a public authority for the purposes of the Environmental Information Regulations 2004.”

The ruling also opens the possibility that other infrastructure operators with statutory powers, including in different sectors, could in the future potentially be treated as public authorities under environmental information law.

ISP Hey! Broadband Discounts 400Mbps to £23 for the FIFA World Cup | ISPreview UK

Original article ISPreview UK:Read More

Internet provider Hey! Broadband, which offers services to homes in various areas covered by the F&W Networks (Fibre and Wireless) full fibre infrastructure – mostly across the South East of England, has discounted their 400Mbps (symmetric) package to £23 per month for new customers that sign-up during the 2026 FIFA World Cup 2026.

The package is available on a 24-month minimum term, including a free installation and wireless router. But take note that a £2 mid-contract price rise does apply, thus the monthly price will increase to £25 from April 2027 and then £27 from April 2028.

NOTE: F&WN is backed by Maestro Capital and Foresight Group LLP. A number of other retail ISPs sell packages via this network, which is said to cover over 410,000 premises (RFS). But we haven’t had any progress updates from them in a long time.

The same 400Mbps package normally starts at £33 per month.

Netomnia UK Brings FTTP Broadband Network to 40,000 Premises in Sale | ISPreview UK

Original article ISPreview UK:Read More

Broadband operator Netomnia (Substantial Group, YouFibre), which has deployed their full fibre (FTTP) network to cover over 3 million UK premises RFS (inc. 500,000 customers), have today confirmed that their deployment across the town of Sale in the Trafford district of Greater Manchester has reached 40,000 premises (RFS).

The original deployment in this area first began in early 2022 and the first homes then went live just before Christmas 2022, with the main build actually completing in 2023 – after 14-months of street works. The work was supported by a private investment of around £10m (c.£250 per premises passed) and is now complete.

NOTE: The Substantial Group is backed by £1.6bn+ of equity and debt from investors Advencap, DigitalBridge, and Soho Square Capital etc. But it’s worth noting that Netomnia is currently in the process of being acquired by the owners of Virgin Media (O2) and nexfibre (i.e. InfraVia, Liberty Global and Telefónica) for £2bn (here).

Sale now sits alongside Didsbury, Cheetham Hill, and Oldham as part of Netomnia’s growing Greater Manchester footprint. Ian Kock, COO at Netomnia, said: “Delivering over 40,000 premises serviceable in Sale reflects how quickly demand for high-capacity connectivity is increasing across communities. Ensuring that homes and businesses have access to infrastructure that can handle that demand is critical, not just for today’s usage, but for how people will work, learn, and operate in the years ahead.”

Netomnia has long held an ambition to extend their FTTP network to reach 5 million UK premises by 2027 (inc. 1 million customers by 2028), although that now seems likely to be a target that will be merged into nexfibre’s future roll-out plans (depending upon the CMA’s competition review). Meanwhile, prices for YouFibre’s broadband packages start at £24 per month for symmetric speeds of 200Mbps on a 12-month fixed-price term and rise to £99.99 for their top 7Gbps tier. All packages include free installation and a Wi-Fi 7 router.